Buying a home is an exciting milestone, but before you start viewing properties or calculating monthly repayments, there’s one part of the process that deserves your attention: your credit profile.
Many buyers spend months saving for a deposit, yet overlook the role their credit score plays in a home loan application. A healthy credit profile can improve your chances of approval, help you qualify for a more competitive interest rate and put you in a stronger position when applying for finance.
At LEAP Home Loans, we regularly work with buyers who assume their income is the only factor banks consider. While affordability is important, lenders also want to understand how you’ve managed credit in the past.
The good news is that if you’re planning to buy a home in the next few months, there are practical steps you can take now to strengthen your credit profile before submitting a home loan application.
What Is a Credit Score?
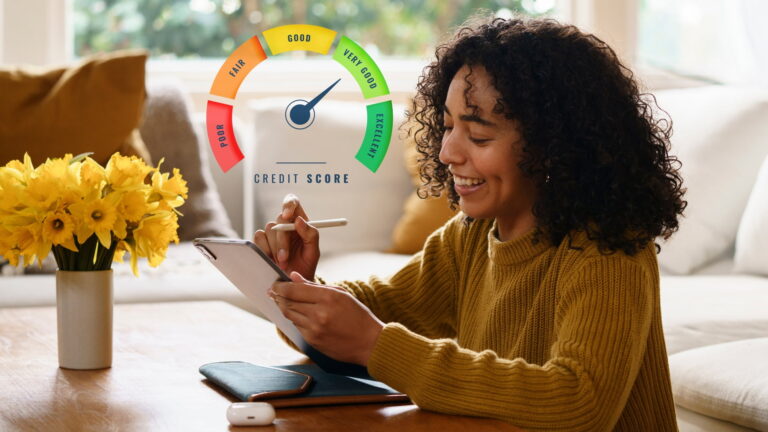
A credit score is a numerical representation of your credit history. It helps lenders assess how you’ve managed debt over time and whether you’re likely to repay future credit responsibly.
Your credit score is based on factors such as:
- Your payment history.
- Existing debt.
- Credit utilisation.
- The length of your credit history.
- Recent credit applications.
Banks don’t rely solely on your credit score when assessing a home loan application, but it plays an important role alongside affordability, income, employment stability and your overall financial position.
Nedbank notes that a credit score of 621 or higher on its Experian-linked scoring system can improve access to personalised lending offers and potentially better interest rates. It’s important to remember that different credit bureaus use different scoring ranges, so the exact number isn’t universal across all lenders.
Why Does Your Credit Score Matter?
A stronger credit profile can make a meaningful difference when applying for a home loan.
While no bank can guarantee approval based on a credit score alone, responsible credit behaviour may improve your chances of:
- Home loan approval.
- Receiving a more competitive interest rate.
- Accessing a higher loan amount.
- Demonstrating financial responsibility to lenders.
It’s possible for two buyers earning similar salaries to receive different home loan offers because their credit histories are different.
This is one of the reasons we encourage buyers to prepare their finances before they begin house hunting.
How to Improve Your Credit Score Before Applying
If you’re planning to buy property within the next three to six months, now is the ideal time to start strengthening your credit profile.
Pay Every Account on Time
Your payment history is one of the most important factors lenders consider.
Late or missed payments can remain on your credit record and may negatively affect future applications.
Setting up debit orders or payment reminders can help ensure every account is paid on or before its due date. Paying earlier or paying more than the minimum amount where possible can also reduce interest costs over time.
Keep Credit Card Balances Low
Having access to credit isn’t necessarily a problem.
Using too much of your available credit, however, may indicate financial pressure.
If you use a credit card, try to keep the balance well below your credit limit. Nedbank recommends using no more than 50% of your available credit limit where possible.
This demonstrates responsible credit management while keeping monthly repayments manageable.
Avoid Multiple Credit Applications
Every time you apply for credit, the lender performs a credit enquiry.
Submitting several applications within a short period can raise concerns because it may suggest you’re relying heavily on borrowed money.
If you’re planning to apply for a home loan soon, avoid opening unnecessary retail accounts, taking out personal loans or applying for multiple credit facilities beforehand.
Check Your Credit Report
Many buyers don’t realise they can check their credit record before approaching a bank.
Reviewing your credit report allows you to:
- Identify incorrect information.
- Check for outstanding accounts.
- Resolve disputes early.
- Understand your current credit position.
Finding and correcting errors before submitting a home loan application can prevent unnecessary delays later.
Reduce Existing Debt
Your overall debt commitments affect more than your credit score.
Banks also assess your affordability and debt to income ratio when considering a home loan application.
Paying down existing debt before applying can improve your affordability and demonstrate responsible financial management.
If possible, focus on reducing high interest debt before taking on a long term financial commitment like a home loan.
Give Yourself Time
One of the biggest misconceptions is that credit scores improve overnight.
In reality, building a stronger credit profile takes consistency.
If you’re hoping to buy property later this year, start preparing several months in advance rather than waiting until you’ve found your dream home.
Small improvements made consistently over time often produce better results than trying to fix everything at the last minute.
What Can Lower Your Credit Score?
Understanding what affects your credit profile is just as important as knowing how to improve it.
Some common factors that may negatively impact your score include:
- Missing account payments.
- Paying accounts late.
- Using most of your available credit.
- Applying for multiple credit facilities within a short period.
- Judgments or adverse listings against your name.
Avoiding these habits can help maintain a healthier credit profile over the long term.
Can You Still Get a Home Loan with a Lower Credit Score?
Yes.
A lower credit score doesn’t automatically mean your application will be declined.
Banks assess a range of factors, including:
- Your income.
- Monthly affordability.
- Existing debt.
- Employment stability.
- Deposit amount.
- Overall financial profile.
Every application is different.
In some cases, improving your credit profile for a few months before applying may strengthen your position. In others, buyers may already qualify despite having a less than perfect credit history.
Rather than making assumptions, it’s often worth obtaining a professional affordability assessment first.
Why Home Loan Pre-Approval Still Matters
Even if you’ve been working on your credit score, one of the smartest steps you can take before searching for property is obtaining a home loan pre-approval.
A pre-approval helps you understand:
- What you may be able to borrow.
- Your realistic purchase budget.
- Whether there are any financial issues worth addressing before making an offer.
If you haven’t already, we recommend reading our guide on How Home Loan Pre-Approval Helps Buyers, where we explain why pre-approval often gives buyers a stronger position when entering the property market.
How LEAP Home Loans Can Help
At LEAP Home Loans, we believe preparation makes all the difference.
We help buyers understand their affordability before they begin searching for property, while comparing offers from multiple participating banks to help secure competitive home loan solutions.
Our service includes:
- Free home loan pre-approvals.
- Affordability assessments.
- Comparing multiple participating banks.
- Guidance throughout the bond application process.
- Support from application through to registration.
Most importantly, our pre-approval service comes at no additional cost to you.
Final Thoughts
Improving your credit score isn’t about chasing a perfect number.
It’s about demonstrating responsible financial behaviour and putting yourself in the strongest possible position before applying for a home loan.
The earlier you begin preparing, the more options you’re likely to have when you’re ready to buy.
If you’re thinking about purchasing a home in Gqeberha, don’t wait until you’ve found the perfect property.
Start with a free home loan pre-approval through LEAP Home Loans. Understanding your affordability, strengthening your credit profile and comparing multiple lenders before making an offer can make your home buying journey far smoother and help you move forward with confidence.